
A comparative market analysis is the document you’ll bring to almost every listing appointment. Build it well and you can defend a price with evidence instead of opinion. Sellers can see exactly how you reached your number.
A comparative market analysis (CMA) is an agent’s written estimate of a home’s likely selling price range. You build it from recently sold, pending, and active homes similar to the one you’re pricing. Those similar homes are called comparables, or “comps.”
This guide walks you through the CMA real estate workflow step by step. You’ll see a worked example with every adjustment dollar shown. You’ll also learn where a CMA ends, where an appraisal begins, and how valuation shows up on the licensing exam.
Table of Contents
- What a Comparative Market Analysis Is and When You’ll Use It
- How to Do a Comparative Market Analysis Step by Step
- Comparative Market Analysis Example With Adjustments
- CMA vs. Appraisal: What Changes When a Lender Is Involved
- The Rules and Ethics Behind Your Opinion of Value
- How CMAs Show Up on the Real Estate Exam
- Frequently Asked Questions
- Practice Your First CMA Before Your Listing Appointment
Key Takeaways
- A CMA gives a price range, not a verdict: It’s an agent’s opinion of likely selling price, built from comps and adjustments. It isn’t an appraisal.
- Comps make or break the analysis: Choose recent, nearby, similar closed sales first. Use pending and active listings to read where the market is heading.
- Adjust the comp, never the subject: If a comp is better than the subject, subtract; if it’s worse, add. This rule shows up on exam questions.
- Reconcile, don’t average: Give the most weight to the comps that needed the fewest adjustments. Keep your final range inside the adjusted prices.
- Know your limits: State law, your broker’s policy, and (for REALTOR® members) the NAR Code of Ethics govern how you present an opinion of value.
What a Comparative Market Analysis Is and When You’ll Use It
A comparative market analysis answers one question: what will a buyer likely pay for this home right now? The answer is a price range, not a single number. No two homes are identical, and no two sales happen under the same conditions.
Licensed agents prepare CMAs under their supervising broker. You’ll pull comps, adjust them for differences, read local market conditions, and land on a range you can explain line by line. Your brokerage may supply templates or software, but the judgment behind the numbers is yours.
If you want a shorter primer first, start with what a CMA is and how agents use it. This guide picks up from there and focuses on how to build one.
How Listing Agents and Buyer’s Agents Use a CMA
Both sides of a deal use the same method to make different decisions:
- On the listing side, you use a CMA to recommend a defensible list price and walk the seller through the evidence.
- On the buyer side, you use a CMA to check whether a list price lines up with recent sales and to build an offer.
Be honest with yourself about bias. A listing CMA can drift high when you’re competing for the listing. A buyer CMA can drift low when your client wants a bargain, so let the comps set the range whatever the goal of the meeting.
What Goes Into a CMA Report
A complete CMA report gives the seller or buyer everything they need to follow your reasoning. Most reports include these parts:
- A subject property summary with size, rooms, lot, age, upgrades, and condition.
- Closed comps, which are the strongest evidence of what buyers actually paid.
- Pending and active listings that show where prices are heading.
- Expired or withdrawn listings, which often point to prices the market rejected.
- An adjustment grid showing each comp’s sale price, adjustments, and adjusted price.
- A market conditions snapshot covering inventory, days on market, and price trends.
- A recommended price range with the basis for your opinion.
How to Do a Comparative Market Analysis Step by Step
Every comparative market analysis follows the same five steps, whether you’re pricing a starter condo or a large single-family home. Practice them in this order until they feel routine:
- Profile the subject property.
- Choose your comparable sales.
- Adjust each comp toward the subject.
- Read the market conditions.
- Reconcile to a price range and write it up.
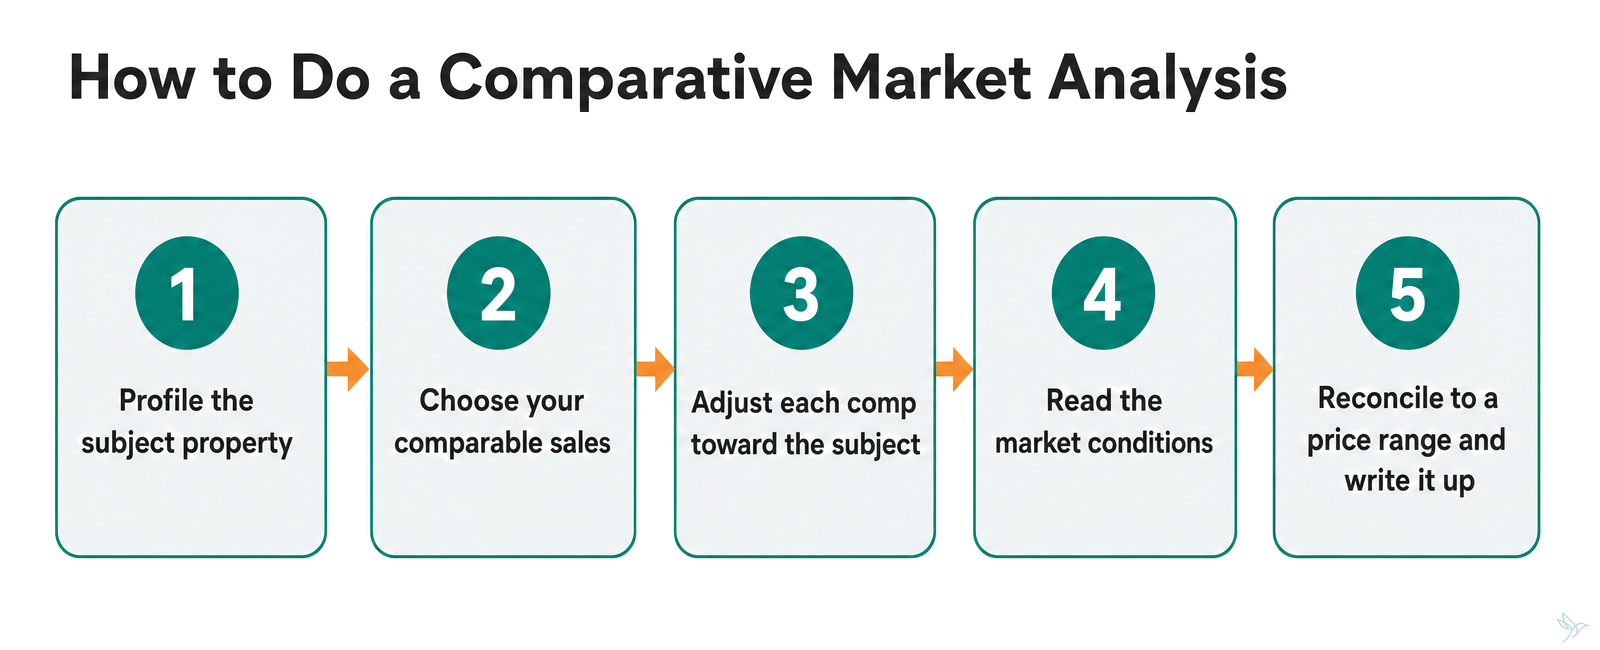
Keep this diagram next to your notes on your first few CMAs and check off each step before you share a price with a client.
The tips inside each step target the mistakes new agents make most often. An error in an early step carries into every number after it.
Step 1: Profile the Subject Property
The subject property is the home you’re pricing. Before you look at a single comp, gather its facts from public records, the multiple listing service (MLS), and a walkthrough. Record these details:
- Property type and style
- Finished square footage
- Bedrooms and bathrooms
- Lot size and age
- Garage spaces
- Upgrades such as kitchens, baths, roofs, and major systems
- Overall condition
- HOA membership and dues
Verify square footage against county records before you go further. If the MLS says 1,900 square feet and the county says 1,800, every size adjustment you make will be off. Ask the seller about recent improvements too, since upgrades don’t always show up in public data.
Step 2: Choose Your Comparable Sales
Comps are the homes you compare against the subject. Look for sales that match it as closely as possible on these points:
- Same market area, ideally the same neighborhood or subdivision
- Similar site, room count, finished area, style, and condition
- Similar legal characteristics, such as zoning and ownership type
- Recent closing dates
It helps to borrow the benchmark appraisers are held to. For appraisals on loans sold to Fannie Mae, Fannie Mae’s comparable sales guidelines require at least three closed comps in the sales comparison approach. They also say comps closed within the last 12 months should be used, with documented exceptions.
That’s a lender standard for appraisals, not a law that governs your CMA. Still, it’s a sound floor for your own work. The same guidance notes the most recent sale isn’t always the best comp. An older sale needing one time adjustment can beat a newer sale needing several.
Pending and active listings add context, but they aren’t sales. Use them to read direction, and treat expired listings as a ceiling signal. Don’t give list prices the same weight as closed prices.
Step 3: Adjust Each Comp Toward the Subject
Here’s the rule that trips up new agents and shows up on exams: you adjust the comp’s sale price, never the subject. The goal is to estimate what each comp would have sold for if it matched the subject.
- If the comp is better than the subject, subtract the value of the difference.
- If the comp is inferior to the subject, add the value of the difference.
Adjustment values should come from local evidence. Fannie Mae’s guidance on adjusting comparable sales says an appraiser’s adjustments must reflect the market’s reaction to the difference between properties. It also says Fannie Mae has no specific net or gross adjustment limits.
So where do the dollar figures come from? Agents commonly draw on three sources:
- Paired sales, meaning two similar homes that differ by one feature, such as a garage bay
- Your broker’s experience with how local buyers value specific features
- Recent local sales data from your MLS
As a new agent, check your adjustment values with your broker before you present them. If a comp needs many large adjustments, drop it and find a closer match. To sharpen your price-per-square-foot math, work through these real estate math practice questions.
Step 4: Read the Market Conditions
Comps tell you what buyers paid. Market conditions tell you whether buyers will still pay that today. Check three numbers for the subject’s area:
- Months’ supply of inventory
- Median days on market
- Sale-to-list price trends
Months’ supply is how many months the current inventory would last at the current sales pace. A rising number means buyers have more homes to choose from.
For national context, NAR’s latest existing-home sales report showed 4.9 months’ supply in August 2026, which NAR called the highest in over ten years. Median time on market was 31 days, and the median existing-home price was $429,100.
Those are national figures, and a CMA prices one home in one neighborhood. Your local MLS numbers matter far more. Pull the same three metrics for the subject’s area and compare them with the months when your comps closed.
Step 5: Reconcile to a Price Range and Write It Up
Reconciliation is the step where you weigh your adjusted comps and reach a final opinion. Give the most weight to the comps that are most similar and most reliable. The comp with the fewest and smallest adjustments usually earns the most weight.
Don’t simply average the adjusted prices, because averaging treats your weakest comp as equal to your strongest. Fannie Mae’s adjustment guidance tells appraisers the indicated value must fall within the range of the comps’ adjusted sale prices. That’s good practice for your comparative market analysis too.
Then write it up. Your finished comparative market analysis should include these parts:
- A subject property summary
- The comp adjustment grid
- A market conditions snapshot
- Your recommended price range
- The basis for your opinion, in plain language a seller can follow
Comparative Market Analysis Example With Adjustments
Here’s a full comparative market analysis example, worked line by line. Every number below is a hypothetical teaching figure, not market data. Real adjustment values depend on your local market and your broker’s guidance.
The subject property has 1,800 square feet, 3 bedrooms, 2 full baths, a 2-car garage, an original kitchen, and average condition. For this example, assume these adjustment values:
- $90 per square foot of size difference
- $10,000 per full bath
- $8,000 per garage bay
- $15,000 for an updated kitchen
Notes you take on finishes and condition during a walkthrough become the adjustment lines in your comp grid.
Each comp differs from the subject in one or two ways. Remember the rule: if the comp is better, subtract; if it’s inferior, add.
- Comp A sold for $400,000. It’s 100 square feet larger (-$9,000) and has an updated kitchen (-$15,000).
- Comp B sold for $372,000. It’s 50 square feet smaller (+$4,500) and has a 1-car garage (+$8,000).
- Comp C sold for $395,000. It matches the subject’s size but has 3 full baths (-$10,000).
Comp | Sale Price | Size | Kitchen | Baths | Garage | Gross Adjustments | Adjusted Price |
|---|---|---|---|---|---|---|---|
Comp A | $400,000 | -$9,000 | -$15,000 | $0 | $0 | $24,000 | $376,000 |
Comp B | $372,000 | +$4,500 | $0 | $0 | +$8,000 | $12,500 | $384,500 |
Comp C | $395,000 | $0 | $0 | -$10,000 | $0 | $10,000 | $385,000 |
Gross adjustments are the total of all adjustments, ignoring whether each one is plus or minus. They give you a quick read on how much work a comp needed to match the subject.
Now reconcile. The adjusted prices range between $376,000 and $385,000. Comp C needed $10,000 in gross adjustments and Comp B needed $12,500, so they’re the closest matches and get the most weight.
Comp A needed $24,000 across two features, so it gets less weight. Leaning on Comp C and Comp B puts the indicated value at about $384,000. A recommended list range of $380,000 to $385,000 sits inside the adjusted range and stays tied to the evidence.
Why not use the simple average of $381,833? It gives Comp A, the least similar comp, the same weight as the two better matches. That pulls your number toward your weakest evidence, which is exactly what reconciliation is meant to prevent.
CMA vs. Appraisal: What Changes When a Lender Is Involved
A CMA and an appraisal use the same comparison logic. Appraisers call it the sales comparison approach, which values a property by analyzing similar sales and adjusting for differences.
What changes is the purpose, the preparer, the standards, and the legal weight. For the appraiser’s side of the process, see how a real estate appraisal works.
According to the Consumer Financial Protection Bureau, an appraisal is a written document that shows an opinion of how much a property is worth. A lender may require one as part of a mortgage.
Appraisers follow the Uniform Standards of Professional Appraisal Practice (USPAP). The Appraisal Foundation calls USPAP the generally recognized ethical and performance standards for the appraisal profession in the United States. Compliance is required for state-licensed and state-certified appraisers in federally related real estate transactions.
Factor | CMA | Appraisal |
|---|---|---|
Who prepares it | A licensed real estate agent, under their broker | An appraiser (state-licensed or state-certified for federally related transactions) |
Purpose | Set a list price or guide an offer | Give a written opinion of value |
Standards | State license law, broker policy, and the NAR Code for REALTOR® members | USPAP |
Lender role | Not prepared for a lender’s loan decision | A lender may require one |
Output | A recommended price range | A written opinion of value |
Here’s why this matters when you prepare a comparative market analysis. If a list price sits far above what the comps support, the buyer’s appraisal may come in below the contract price. That can force a renegotiation or stall the financing, so pricing to the comps protects the deal later.
The Rules and Ethics Behind Your Opinion of Value
Your opinion of value carries professional duties. If you’re a REALTOR® member, NAR’s 2026 Code of Ethics applies. Article 11 says REALTORS® shouldn’t provide specialized services outside their field of competence.
Standard of Practice 11-1 adds specifics for opinions of value. You need to know the property type, have access to the information you need, and be familiar with the area. If you’re missing any of these, you must disclose that to the requester in advance.
The same standard covers opinions of value you prepare outside a listing pitch or buyer-offer help. Those opinions must include several items, among them a statement that the opinion is not an appraisal.
These practical guardrails apply whether or not you’re a REALTOR® member:
- Don’t inflate a CMA to win a listing; the comps set the range.
- Label your work as an opinion of price, not an appraisal.
- Check your state’s license law and your broker’s policy before giving opinions of value outside a listing.
- Ask your broker before preparing a broker price opinion (BPO), an estimate of value prepared by an agent or broker.
How CMAs Show Up on the Real Estate Exam
Valuation is tested content. Pearson VUE’s national salesperson exam content outline puts Property Value and Appraisal at 11 of 80 scored items on the national portion. That section lists Comparative Market Analysis (CMA), Broker Price Opinion (BPO), and the sales comparison approach.
That count applies to the national portion of exams Pearson VUE builds. Your state portion and exams from other vendors may differ, so check your state’s candidate handbook.
Focus your practice on three skills:
- Getting adjustment direction right every time
- Calculating price-per-square-foot differences quickly
- Knowing which valuation approach fits which property type (sales comparison, cost, or income)
Sample Exam Question on Adjusting a Comp
A comparable sold for $372,000 and has a 1-car garage. The subject has a 2-car garage, and the local market values a garage bay at $8,000. What is the comp’s sale price after the garage adjustment?
- A. $364,000
- B. $372,000
- C. $380,000
- D. $388,000
Answer: C, $380,000.
Explanation: The comp is inferior to the subject because it has one fewer garage bay. You add $8,000 to the comp’s price: $372,000 plus $8,000 equals $380,000.
Choice A is the trap. It subtracts the garage value, which means you adjusted in the wrong direction.
Frequently Asked Questions
How Many Comps Should a CMA Include?
At least three closed sales is a sound baseline. That matches Fannie Mae’s minimum for appraisals on loans sold to Fannie Mae, which many agents borrow as a benchmark. Add pending and active listings for context on where prices are heading.
Is a CMA the Same as an Appraisal?
No. A CMA is an agent’s opinion of a likely selling price range, used for pricing and offers. An appraisal is a written opinion of value from an appraiser following USPAP, and a lender may require one.
Do Agents Charge for a CMA?
Practices vary by brokerage and state. Many agents prepare a CMA as part of pursuing a listing or helping a buyer make an offer. Check your broker’s policy before you discuss any fee.
How Long Is a CMA Good For?
A CMA holds up only as long as market conditions do, and there’s no fixed expiration. Refresh it when new comps close, listings go pending, or local inventory shifts.
Can a New Agent Do a CMA?
Yes. Pre-licensing covers the concepts, and your broker reviews your early CMAs before they reach a client. If you’re a REALTOR® member, SOP 11-1 also expects competence in the property type and area, so start with neighborhoods you know.
Practice Your First CMA Before Your Listing Appointment
Every comparative market analysis follows the same path. Profile the subject, choose close comps, adjust the comp toward the subject, read local conditions, and reconcile to a range inside the adjusted prices. Then disclose the limits of your opinion.
The fastest way to build the skill is practice. Pick a recently sold home in your area, build a CMA without looking at the final price, and compare your range to the actual sale. Review it with your broker or instructor.
Next, see what to include in your listing presentation. Then learn how to price a home and talk sellers through it.
If you’re not licensed yet, valuation is where pre-licensing pays off. When you start your real estate pre-licensing course with Colibri Real Estate, you’ll work through the sales comparison approach and adjustment math in state-specific lessons. Instructor support and Rubi AI Tutor help when a concept doesn’t click.
Colibri’s Pass or Don’t Pay guarantee backs your exam prep, though it isn’t available in Florida, Michigan, New Jersey, or Tennessee. More than 1.5M students have trained with Colibri. For a guided starting point before you enroll: Master Real Estate FREE Starter Kit Here.


